
Depending on the nature of seasonal fluctuations, two types of models are distinguished – additive and multiplicative.
According to the additive model, the time series with seasonal fluctuations is represented as:

where:  is the value of the predicted variable for
 the -th point in time;
 – trend component;

 – seasonal component;

 – Accidental error.
According to the multiplicative model, the time series with seasonal fluctuations has the form:

To solve the question of which of the considered models should be chosen for a particular time series, it is necessary to build a graph of changes in the predicted value over time and analyze the change in the amplitude of seasonal fluctuations (Fig. 16.). If the amplitude of seasonal fluctuations does not have a pronounced tendency to change over time, then an additive model (a) can be chosen, otherwise a multiplicative model (b) is preferred.
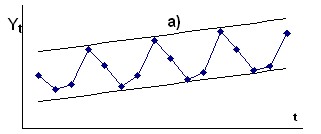
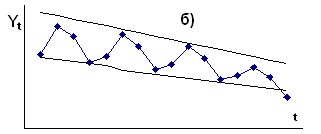
Fig. 16. Time series characteristic of the additive (a) and multiplicative (b) models.
The most simple seasonal component can be determined using moving averages with an averaging period equal to the period of seasonal fluctuations L.
The moving average is a variable whose values are equal to the arithmetic mean of the quantity under study at the point for which it is calculated and the values of all points separated from it by 0.5 * (L – 1) left and right if L is odd and 0.5L is even. When calculating the moving average value for the next point in the time series, the numbers of the points involved in the calculation are shifted by one. The length of the period of seasonal fluctuations is the number of time intervals through which the nature of the change in the time series is repeated.
Thus, to calculate the moving average, it is first necessary to determine the length of the period of seasonal fluctuations L. In the simplest case, it can be found on the basis of visual analysis of the data. Then, for each point in the original time series, it is necessary to calculate the average values of the variable  . If L is even, the resulting series of moving averages CSt is shifted relatively
 by an amount equal to half of the time interval. The values of the moving average do not correspond to specific intervals, for example, the first or second interval, but to the second half of interval 1 and the first half of interval 2 (Fig. 17). The next value of the moving average corresponds to halves of intervals 2 and 3, etc. The moving average shifted by half of the interval is called the interinterval moving average. To eliminate the resulting bias, the resulting moving averages with any even averaging period must be averaged again with an averaging period of two. The moving average obtained as a result of repeated averaging is called the centered moving average.
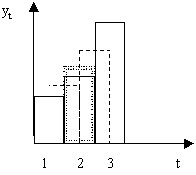
Rice. 17. Obtaining centered moving averages with an averaging period of two. Where is:
 – yt values;
 – Interinterval moving averages for points 1-2 and 2-3, respectively;
 – Interval moving average for point 2.
As can be seen from the calculation scheme, as a result of averaging, the number of moving average values is less than the number of points of the original time series by an amount equal to the averaging period L since there are no points necessary for finding the moving average at the edges of the time series. The loss of L points leads to the fact that the minimum duration of the time series should be equal to at least three periods of oscillation.
The scheme for calculating moving averages for the averaging period of four (quarterly data for several years) is presented in Table 1.
Table 1.
| perio-da t number | actual values of the series | interinterval moving averages CCt | interval (centered) moving averages of the CASt |
| 1 |
| ||
| 2 |
| ||
|
| |||
| 3 |
|
| |
|
| |||
| 4 |
|
| |
|
| |||
| 5 |
|
| |
|
| |||
| 6 |
| ||
| 7 |
| ||


The further scheme for determining seasonal fluctuations is different for additive and multiplicative models, so we will consider them separately.